Tax Season Without a Safety Net: What Indian Professionals on US Visas Actually Owe (And What They're Leaving Behind)
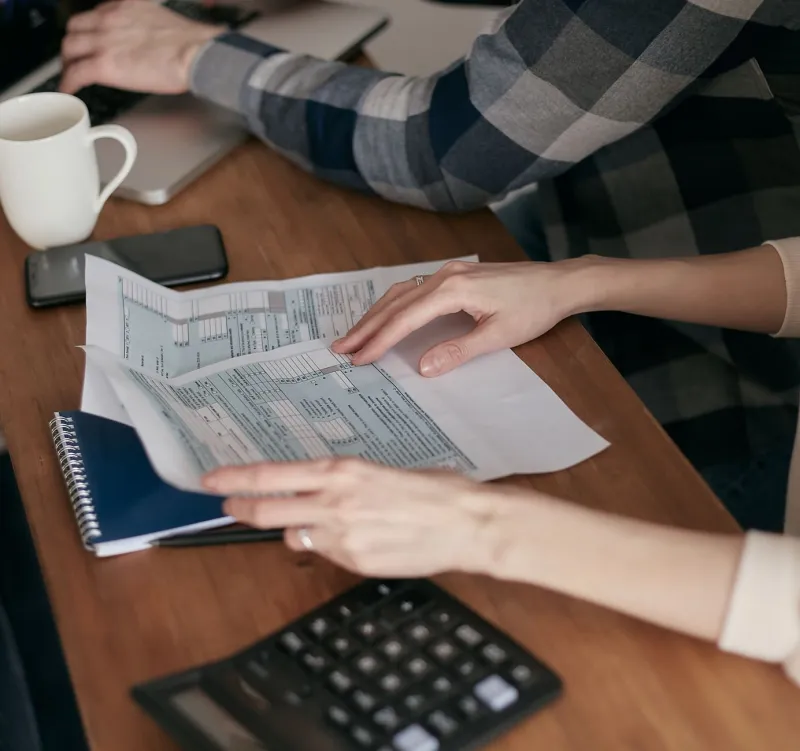
Every spring, thousands of Indian professionals on H-1B, L-1, OPT, and green card applications sit down with TurboTax, click through a dozen screens, and quietly wonder if they're doing this right. Spoiler: a lot of them aren't — not because they're careless, but because the US tax system has layers that nobody explains during your visa interview or your first-week HR orientation.
This isn't a substitute for a CPA (seriously, get one if your situation is complicated). But it is the plain-language primer that should have come in your welcome packet.
Your Visa Status Changes Everything — Including How the IRS Sees You
Before you even think about deductions, you need to know how the IRS classifies you. It's not about citizenship — it's about residency for tax purposes, and those are two very different things.
The IRS uses something called the Substantial Presence Test to decide whether you're a "resident alien" (taxed like a US citizen on worldwide income) or a "nonresident alien" (taxed only on US-sourced income, using a separate form — Form 1040-NR).
The math: if you've been physically present in the US for at least 31 days in the current year and 183 days over the past three years (using a weighted formula), you're a resident alien for tax purposes.
Why this matters for Indian professionals: If you arrived mid-year on an H-1B, you might be filing as a dual-status alien — resident for part of the year and nonresident for the rest. This creates a genuinely messy return that most off-the-shelf tax software handles poorly. A dual-status return has its own rules about which deductions you can claim and how you report foreign income.
The Deductions H-1B Workers Almost Always Miss
Let's talk money you're leaving on the table.
Visa and immigration fees: If your employer required you to pay any portion of your H-1B filing fees (which technically they're not supposed to, but it happens), those legal and professional fees may be deductible as job-related expenses — particularly if you're self-employed or itemizing. Even if your employer paid, attorney fees you personally paid related to maintaining your work authorization are worth flagging to a tax professional.
Relocation expenses: The 2017 Tax Cuts and Jobs Act eliminated moving expense deductions for most people — but not for active-duty military. If you're a civilian professional who relocated from India for a US job, this deduction is unfortunately gone for federal purposes. However, several states still allow it. If you moved to California, New York, or Massachusetts, check your state return separately.
Home office deduction (if you're self-employed or on certain visa categories): If you're on an OPT STEM extension doing freelance or contract work, or if you're a Schedule C filer, the home office deduction is real and significant. The IRS allows you to deduct a portion of your rent or mortgage based on the percentage of your home used exclusively for work. Remote workers employed by a company (W-2 employees) cannot take this deduction at the federal level post-2017 — but again, some states differ.
Professional development and credential costs: Exam fees for certifications like AWS, PMP, or CPA (if you're already working in that field), plus relevant courses and textbooks, may be deductible if they maintain or improve skills in your current profession. Costs for switching careers don't qualify.
Working Remotely from India for a US Company? The FEIE Is Your Friend
This one's for the growing crowd of Indian professionals who work for US employers while based in India — either permanently or during extended visits.
If you qualify as a US tax resident (based on the Substantial Presence Test or a green card) but spent significant time physically working outside the US, you may be eligible for the Foreign Earned Income Exclusion (FEIE). For 2024, this exclusion shields up to approximately $126,500 of foreign-earned income from US federal income tax.
To qualify, you need to pass either the Bona Fide Residence Test (you've established genuine residence in a foreign country for a full tax year) or the Physical Presence Test (you were outside the US for at least 330 full days in any 12-month period).
The catch: The FEIE applies to income you earned while physically outside the US. If you're splitting time between the US and India, you need to track your days carefully. And if your employer is a US company paying you in dollars to a US bank account, the income is still potentially excludable — what matters is where you performed the work, not where the money comes from.
Pair the FEIE with the Foreign Housing Exclusion, and you could also exclude a portion of housing costs paid abroad. This combination is underused by Indian professionals who assume it only applies to expats working for multinational corporations.
The India-US Tax Treaty: Real Benefits, Real Limitations
India and the United States have a tax treaty that's been in place since 1989. It's not the most generous treaty in the world, but it does a few useful things:
- Prevents double taxation on certain categories of income, including dividends, interest, and royalties
- Provides relief for students and trainees — if you're on an F-1 or J-1 visa and receiving stipends or fellowships, treaty provisions may reduce your US tax liability
- Allows a foreign tax credit — if you paid taxes to the Indian government on income also taxed by the US, you can generally claim a credit (Form 1116) to offset your US tax bill dollar-for-dollar
The foreign tax credit is particularly valuable if you have rental income from property back in India or investment returns from mutual funds and fixed deposits. Many Indian professionals dutifully pay TDS (Tax Deducted at Source) in India and then forget to claim the corresponding US credit. That's money left behind.
FBAR and FATCA: The Reporting Requirements That Carry Scary Penalties
This isn't a deduction — it's a warning.
If you have financial accounts in India with a combined value exceeding $10,000 at any point during the year, you're required to file an FBAR (FinCEN 114). This is separate from your tax return and has its own deadline (April 15, with an automatic extension to October). Failure to file can result in penalties starting at $10,000 per violation — even if you owe no additional tax.
FATCA (Form 8938) kicks in at higher thresholds ($50,000 for single filers living in the US) and is filed with your regular tax return. Indian banks and financial institutions are increasingly reporting account information to the IRS under FATCA agreements, so the "they'll never know" approach is genuinely risky.
NRI fixed deposits, savings accounts, PPF accounts, and even certain mutual fund holdings may all trigger these requirements. Check your balances and file accordingly.
One More Thing: State Taxes Are Not Optional
Federal taxes get all the attention, but if you're living in California, New York, New Jersey, or Illinois, your state income tax bill can rival your federal one. Some states — like California — don't fully conform to federal tax rules, which means deductions or exclusions you claimed federally might not apply at the state level.
If you moved between states during the year (say, relocated from Texas to California for a new job), you'll file part-year resident returns in both states. This is another scenario where DIY tax software tends to produce questionable results.
The Bottom Line
Tax season for Indian professionals in the US isn't just Form 1040 and a W-2. Between visa status classifications, treaty provisions, foreign account reporting, and state-level quirks, there are enough moving parts to make even a senior engineer's head spin. The good news: most of these rules have legitimate money-saving angles if you know where to look.
Finding a CPA who specifically works with nonresident and dual-status filers — ideally one familiar with the India-US context — is worth every dollar of their fee. And starting the conversation in January rather than April 14th? That's the career-smart move nobody talks about but everyone should make.